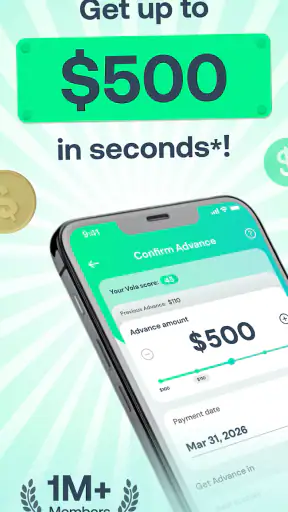
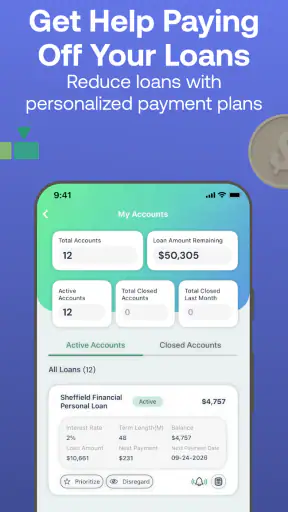
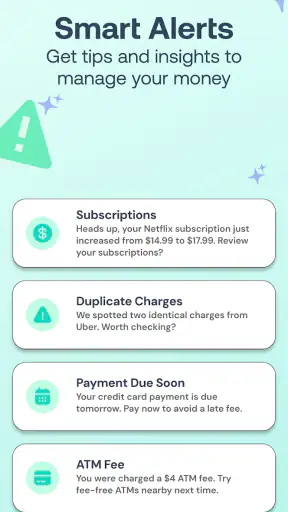
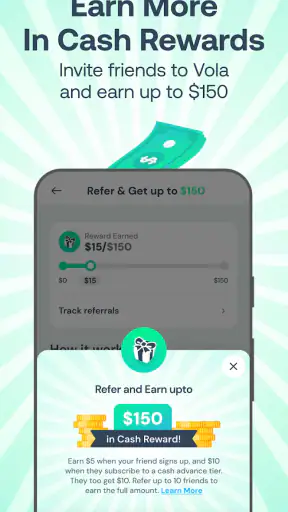
When an unexpected bill lands before payday, I understand why an app such as Vola: Cash Advance & Credit looks appealing. It is a finance app from Vola inc. built around short-term cash access, spending awareness, budgeting, and credit-building tools. I would not treat it as a replacement for steady income or a complete banking service, but it can be useful when the problem is a small timing gap and I already have a clear plan for the next deposit.
What makes the app worth examining is the complete journey rather than the promise on its own. You begin with a financial shortfall, connect the information needed for the service, review what is available, and then decide whether taking an advance actually improves the situation. In my experience, that last decision matters more than the speed of the first steps. Easy access to money is helpful only when the repayment fits comfortably into the rest of the month.
From a tight week to a workable plan
A realistic example is a utility payment arriving several days before payday. I would first open Vola to understand whether an advance could cover that specific gap, rather than borrowing a vague amount for general spending. That distinction is important: assigning the money to one known expense makes it easier to judge the outcome and avoid turning a temporary delay into a repeating borrowing cycle.
The app is free to download and carries an Everyone content rating, so it is presented for a broad audience. Its focus is narrower than a traditional bank app. Instead of being mainly a place to hold deposits, pay merchants, or manage a full range of accounts, it centers on short-term financial support and visibility into everyday money habits. That makes it more relevant to someone managing cash flow than to someone looking for a complete replacement for their bank.
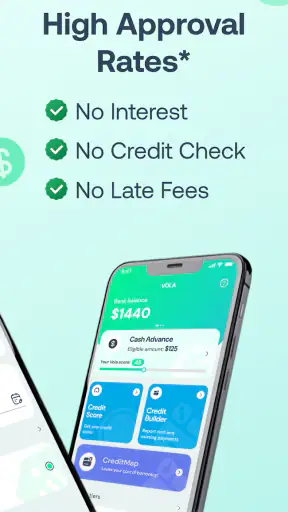
Before using any cash advance service, I would check the total cost, repayment timing, eligibility conditions, and the effect on the next pay period. The phrase “no credit check” may be attractive to someone with limited credit history, but it should not be interpreted as risk-free access. A decision based only on urgency can overlook the more important question: will the next income payment still cover rent, food, transport, and other fixed commitments after the advance is handled?
Preparing the request instead of rushing it
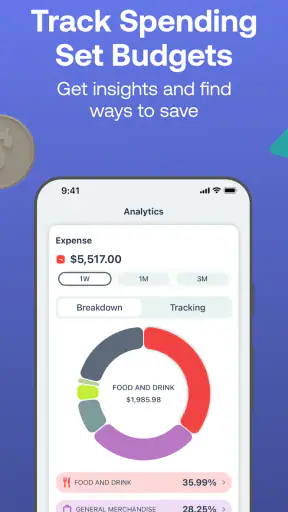
The most useful first step is to gather a simple picture of the coming week. I would note the amount needed, the date of the bill, the expected date of income, and the payments already scheduled. Vola’s budgeting and spending-tracking focus can support that review, but the app cannot make an unaffordable repayment affordable. The quality of the decision still depends on the information I bring to it.
I would also separate an emergency from a convenience purchase. A necessary prescription, transport to work, or an overdue household bill has a different place in the budget from an impulse purchase. If the request is for something optional, waiting is usually the safer alternative. This is one of the less obvious trade-offs with any fast cash tool: the easier the request feels, the more discipline is needed before pressing ahead.
Vola is listed as a free app, but that does not mean every financial transaction or service connected with an advance should be assumed to have no cost. I would read the in-app terms carefully before accepting anything. The relevant comparison is not the download price; it is the complete obligation created by the advance and the way it fits with my next income cycle.
Moving through the app’s financial handoffs
The workflow depends on several handoffs. I provide financial information, the service evaluates what it can make available, and I then review the proposed amount and timing. After that, the money has to reach the intended destination, while repayment must later be coordinated with the income that was expected to cover it. Each handoff is a point where an assumption can become a problem.
For example, an expected deposit may arrive later than planned, or a bill may be larger than I remembered. A responsible workflow therefore includes a buffer. I would avoid requesting the maximum amount simply because it appears available, and I would not count money as safely repayable until essential expenses have been removed from the next paycheck. This approach makes the app a planning aid rather than a substitute for planning.
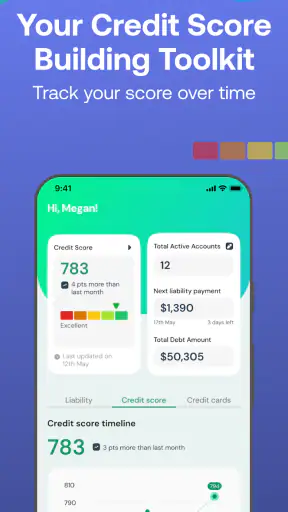
The credit-building side deserves the same careful reading. Building credit is not an instant result of downloading a finance app. It depends on the particular product terms and on handling obligations as required. I would look closely at how the credit-related feature works, what actions are expected, and whether it matches my longer-term goal. Someone trying to establish a financial record may find that useful, but someone who only needs emergency cash should not assume the two purposes are identical.
Spending tracking can be valuable after the request, not just before it. I would use it to watch whether the advance solved one isolated problem or merely created room for other spending. That is a practical test: if the balance disappears quickly despite the advance, the deeper issue may be timing, recurring expenses, or an incomplete budget. In that situation, repeating advances could hide the cause instead of fixing it.
What the outcome looks like in everyday use
Suppose I use the app to bridge a short gap for a necessary bill. The best outcome is not simply receiving money. It is reaching payday without missing the bill, knowing exactly how the repayment affects the next budget, and avoiding a second request. I would then review the spending record and adjust the following week’s plan, perhaps by moving a discretionary purchase or setting aside part of the next deposit earlier.
This is where Vola can feel more useful than a bare borrowing interface. Its combination of cash access, budgeting, and spending visibility encourages me to connect the immediate decision with the rest of my finances. The tools are most helpful when I use them before the crisis becomes urgent and keep checking the result afterward. A cash advance alone handles the symptom; the surrounding financial tools can help me understand the pattern.
The app has attracted a 4.7 average from around 11 thousand ratings, with roughly 2.1 thousand written reviews, and it has passed 500 thousand installs. Those figures suggest that many people have found the service relevant enough to try, but they do not tell me whether it will suit my income schedule or financial habits. User popularity is a useful signal for visibility, not a guarantee that an advance is appropriate in every situation.
In practical terms, I would recommend keeping a record of the request, the expected repayment date, and the essential expenses that must come first. If the app shows spending activity that I do not recognize, I would investigate it before making another decision. If the cash arrives later than the bill deadline, the original problem may remain, so timing should be confirmed rather than assumed.
Where this workflow becomes uncomfortable
The biggest weakness is built into the category: a fast advance can make a difficult month look manageable while reducing flexibility in the next one. If income is already too low for regular expenses, borrowing may only move the shortfall forward. I would skip Vola when I need money repeatedly for groceries, rent, or other basic costs and have no realistic way to absorb the repayment. That situation calls for a broader budget review or direct assistance, not a series of temporary advances.
Another friction point is that financial apps require trust and attention. I would not rush through account connections, permissions, identity steps, or agreement screens simply because I was anxious about a bill. I would verify every amount and date shown before continuing. A small misunderstanding at the beginning can affect the entire handoff from request to repayment.
The app may also be the wrong choice for someone who wants predictable, long-term borrowing. A conventional personal loan, a credit-union option, or an arranged overdraft may be easier to compare when the need extends beyond one pay cycle. Those alternatives can involve their own requirements and costs, but they are better suited to a planned, larger obligation than repeatedly using a cash-advance product for an ongoing deficit.
Likewise, someone mainly seeking detailed investment tools, joint-account management, extensive bill payment features, or a full banking relationship should look elsewhere. Vola’s identity is centered on short-term cash flow and financial awareness. Its value is strongest when that is exactly the problem I am trying to solve, not when I expect one app to cover every financial task.
How I would use it more safely
I would set a personal borrowing rule before opening the request screen. For instance, I would only consider an amount tied to a necessary expense and only when the next income payment could cover the obligation without sacrificing essentials. I would also leave room for ordinary surprises, because a budget that works only if nothing goes wrong is not a reliable budget.
A second useful habit is to review spending before and after the advance. Beforehand, this helps identify whether the shortage is genuinely temporary. Afterward, it shows whether the money went where intended and whether another expense has simply taken its place. This two-stage review is more informative than checking the balance once and assuming the problem has disappeared.
For credit-building goals, I would treat the feature as a longer-term project and read the relevant instructions rather than relying on the general idea that using the app automatically improves a credit profile. I would also avoid taking an advance solely to chase a credit outcome. The immediate repayment obligation should make sense on its own.
The current version is 3.4.15 and the app requires at least iOS or Android version 9. That makes it accessible on a range of older supported devices, which is helpful for people who do not replace their phone frequently. Even so, I would keep the app updated when possible and make sure I can access important account information if my phone, connection, or login method becomes unavailable at a critical moment.
My recommendation after following the full journey
I see Vola as a focused tool for a specific problem: a short-lived mismatch between when money is needed and when income arrives. The combination of cash advances, budgeting, spending tracking, and credit-oriented features gives the experience more depth than a simple request-and-receive service. I especially like the possibility of using the tracking tools to examine what caused the shortfall rather than immediately repeating the same action.
Still, I would recommend it only to someone who understands the repayment path before accepting an advance. The app can help with a genuine timing issue, but it cannot repair an income gap that appears every month. Anyone considering it should compare the obligation with their next full budget, read the terms carefully, and decide whether a bank, credit union, employer option, or trusted personal arrangement would be more suitable.
My final view is cautiously positive. Vola inc. has created a finance app that can be practical when used with a narrow purpose and a clear exit plan. I would use it as a temporary bridge and a way to inspect spending habits, not as permission to spend ahead of income. The safest result is not getting cash quickly; it is solving the immediate problem without creating a larger one on payday.


